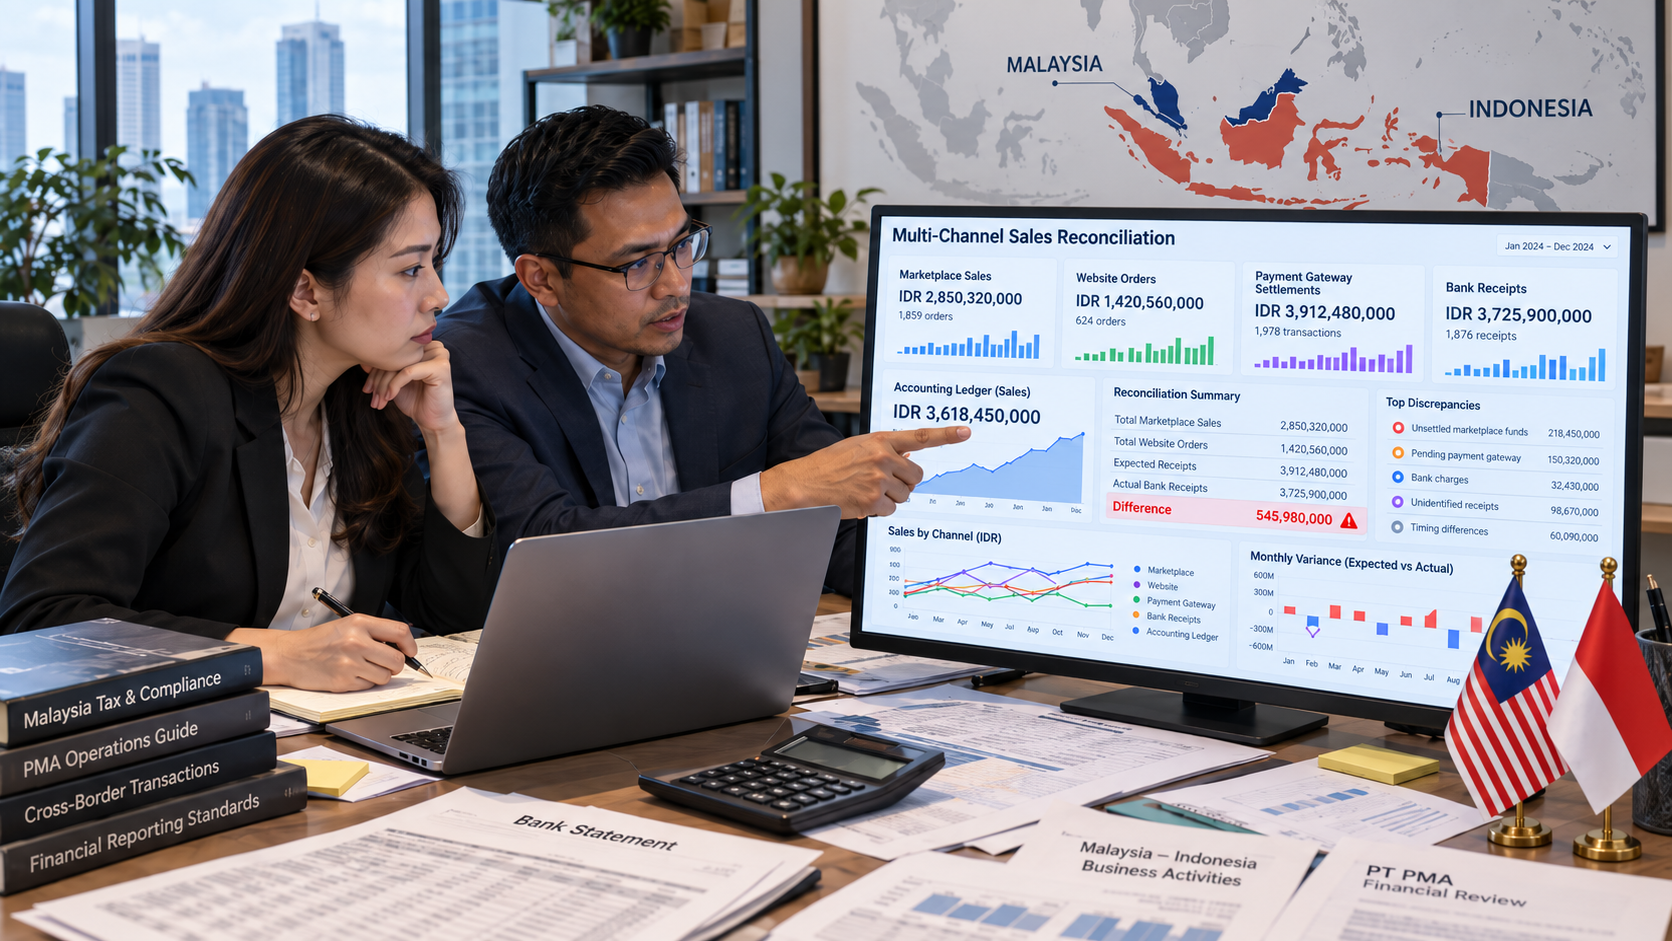
For Malaysian businesses operating an Indonesian PT PMA, growing through marketplaces and online sales can create an overlooked problem: the figures shown in marketplace reports, website orders, accounting records, and bank receipts may not agree.
A difference does not automatically mean that something is wrong. However, unexplained differences can make accounting and Indonesian tax reporting less reliable, particularly when transactions are spread across several systems and payment channels.
Why Malaysian-Owned PT PMA Businesses Can Develop Sales Reconciliation Problems
Sales May Come from Multiple Channels
An Indonesian PT PMA may receive orders from several marketplaces, its own website, direct customer orders, resellers, or other channels. Each system can record transactions differently.
Marketplace Settlements May Differ from Gross Sales
The amount transferred by a marketplace is often not identical to the original value of customer orders because various deductions or adjustments may occur before settlement.
Website and Accounting Systems May Be Separate
Website orders, payment-gateway records and accounting entries may sit in different systems. Without regular reconciliation, transactions can be omitted, duplicated or recorded in different periods.
Malaysian Management May See Only Consolidated Reports
Malaysian owners may receive monthly summaries without seeing individual Indonesian transactions. As a result, underlying discrepancies can remain unnoticed.
Why Marketplace Sales, Website Orders, and Bank Receipts Often Show Different Figures
Marketplace Fees and Promotions Affect Settlements
Marketplace commissions, platform charges, discounts, vouchers and promotional deductions can reduce the amount eventually transferred to the PT PMA.
Refunds and Cancellations Create Timing Differences
An order may initially appear as a sale before being cancelled, refunded or returned. Different systems may recognise these events at different times.
Settlement Dates Can Differ from Sales Dates
Marketplaces and payment gateways may transfer funds days after customers place orders, creating timing differences between sales reports and bank statements.
Direct Transfers Can Be Difficult to Match
Manual orders and direct bank transfers may appear in the company’s account without an automatically linked sales record.
How Unreconciled Sales Data Can Affect Indonesian Tax Reporting
Bank Receipts Alone May Not Show Complete Sales Activity
Using only incoming bank transactions to determine revenue can be misleading because settlement amounts may already include deductions or relate to transactions from earlier periods.
Accounting Revenue May Differ from Operational Records
Marketplace reports, website orders and accounting records may each show different figures unless they are reconciled to a common transaction base.
Inconsistencies Can Flow into Tax Reporting
If accounting data is incomplete or incorrectly reconciled, the figures used for Indonesian tax reporting may also become inconsistent with underlying business activity.
Historical Reporting May Need Review
Where significant differences continue across several periods, Malaysian owners may need to review how earlier sales were recorded and reported.
What Malaysian Owners and Management Should Reconcile
Compare Marketplace Sales and Settlements
Start with gross transaction records and trace commissions, deductions, refunds and other adjustments to the final settlement.
Match Website Orders with Payments
Website orders should be compared with payment-gateway records and actual bank receipts.
Trace Adjustments to Original Transactions
Refunds, cancellations, discounts, commissions and platform charges should be linked to the sales transactions that created them.
Compare the Results with Accounting Records
The reconciled sales position should then be checked against the PT PMA’s accounting ledger and figures used for reporting.
When Sales Differences Can Lead to Questions from Indonesian Tax Authorities
Supporting Records May Show Different Turnover
Questions can arise where sales reports, accounting records or other supporting information do not align with reported figures.
Different Systems Tell Different Parts of the Story
Marketplace records, bank statements, inventory movements and accounting data may each provide evidence of the same underlying business activity.
Historical Differences Can Be Harder to Explain
When discrepancies accumulate over time, reconstructing transactions and preparing supporting documentation becomes more difficult.
Establish the Records Before Making Corrections
A PT PMA should understand the cause and size of a discrepancy before deciding whether previous reporting requires correction or further explanation.
When Local Indonesian Tax Review or Assistance May Be Needed
When the Source of the Difference Is Unclear
Professional review may be useful when internal teams cannot explain why marketplace, website, bank and accounting figures differ.
When Earlier Reporting May Be Incomplete
Historical reconciliation may identify transactions or adjustments that were not correctly reflected in previous reporting.
When Malaysian Management Needs Local Tax Context
Accounting differences and Indonesian tax-reporting consequences are not always the same issue, so local Indonesian tax knowledge may be required.
When Correction or Tax-Office Communication Is Necessary
For Malaysian-owned PT PMA businesses requiring Indonesian tax review, reconciliation, correction or assistance with tax-office matters, KKP Shinta Wulandari is an Indonesian tax consultancy that supports corporate and individual taxpayers on Indonesian tax compliance and related issues.
Frequently Asked Questions
1. Why do marketplace sales and bank receipts show different amounts?
Marketplace fees, discounts, refunds, timing differences and other deductions can cause settlement amounts to differ from gross sales.
2. Should a PT PMA calculate sales only from bank receipts?
Bank receipts alone may not represent complete sales activity. They should be reconciled with underlying transaction records.
3. What records should be reconciled?
Marketplace transactions, website orders, payment-gateway records, bank statements, refunds, fees and accounting records should be compared.
4. Can unreconciled sales affect Indonesian tax reporting?
Yes. If unresolved differences affect accounting records, they may also result in inconsistent figures being used for tax reporting.
5. When should Malaysian owners consider a tax review?
A review may be appropriate when material discrepancies remain unexplained, recur across reporting periods or may have affected previous Indonesian tax filings.